Fuel Procurement Intelligence and Micro-Hedging Platform for Independent Gas Stations
The US convenience store industry sold $476.3 billion in motor fuel in 2025, according to NACS. Of the 122,620 stores selling fuel, 63% are single-store operators. They buy wholesale gasoline and diesel from regional distributors called jobbers, who email them a new price every evening at 6 PM. That price is the rack price at a nearby terminal, plus the jobber's markup, plus delivery. The independent station owner has almost no visibility into whether that markup is fair, no ability to time purchases against spot market movements, and no access to the hedging instruments that Costco and Walmarts use to smooth out volatility. The information asymmetry between a single-store operator in Nutley, New Jersey, and a refiner in Houston is total.
The Problem
Fuel retailing in America runs on a peculiar information structure. Refiners set wholesale "rack" prices at approximately 220 terminal locations across the country. These prices reset daily, typically around 6 PM local time, and they move in response to spot market shifts, pipeline logistics, seasonal blend transitions, and refiner inventory positions. The rack is the wholesale starting point. Everything after it is markup.
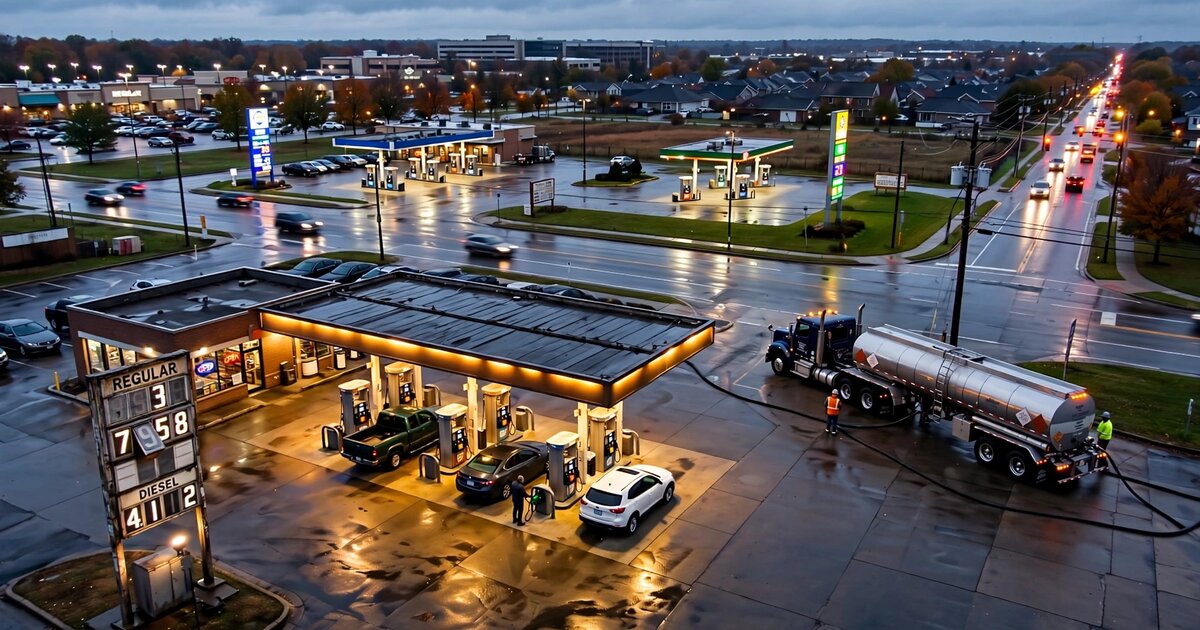
Between the rack and the retail pump sits a distribution layer: jobbers, branded wholesalers, and supply contract intermediaries. A jobber buys fuel at the rack, adds a margin of $0.03 to $0.10 per gallon, loads a tanker truck, and delivers to the station. The station owner's cost per gallon is rack + jobber markup + delivery surcharge. That cost determines whether the owner makes money that day, breaks even, or sells fuel at a loss while hoping to make it back on Gatorade and cigarettes inside.
Here is the structural problem. The station owner receives a single price from a single jobber at the end of each day. There is no comparison shopping. There is no visibility into what the rack actually was that morning across different terminals within trucking range. There is no way to know if the jobber's markup jumped from $0.04 to $0.08 because the jobber's own costs rose, or because the jobber simply decided to take more margin that week. The owner has one supplier, one price, and no leverage.
An NPR interview in June 2026 with independent station owner Ajit Gill captured the dynamic perfectly: "We get pricing every day. End of the day, you will get an email saying, this is going to be your cost starting 6:00 PM this evening. So any fuel that arrives after that point is going to be at that price." Gill described the competitive disadvantage against Costco bluntly: "They probably have more access and insight as well as relationships than a small guy, where you're pretty much dependent on the pricing you're going to get, and it is what it is."
That last sentence is the entire business case for this startup. "It is what it is" should not be the procurement strategy for a business spending $2-5 million per year on its primary input cost.
The Numbers
The 2026 NACS/NIQ TDLinx Convenience Industry Store Count reports 151,975 convenience stores in the United States as of December 31, 2025. Of those, 122,620 sell motor fuel. The industry sold $476.3 billion in fuel in 2025 at an average retail price of $3.11 per gallon.
The ownership structure is where the opportunity lives. Companies operating 10 or fewer stores own 95,672 locations, representing 63% of the total. NACS estimates that roughly 55% of fuel-selling convenience stores are true single-store operators: about 64,000 stores nationwide. These are family businesses. Harry Singh in Nutley. Ajit Gill in his market. Individual entrepreneurs who signed a supply contract with a jobber years ago and haven't renegotiated since.
Approximately 50% of US fueling outlets sell "unbranded" fuel, meaning they purchase on the open market or through unbranded contracts rather than carrying a refiner's flag. These unbranded operators have the most pricing freedom at the pump but also the most exposure on procurement, because they lack the supply agreements and volume protections that come with a branded contract.
The gross margin on fuel tells the story of how tight the business is. Over the past five years, retailer gross margins have averaged 27.2 cents per gallon, or about 10.7% of the retail price, according to NACS. But that is a gross figure before credit card processing fees (which consumed a record $21.3 billion industry-wide in 2025), labor, utilities, insurance, and the mortgage on the property. Net profit on fuel sales at many independent stations is effectively zero. The entire business model depends on getting customers out of their cars and into the store, where a fountain drink carries a 70% margin.
When your net fuel margin is measured in fractions of a penny, a procurement improvement of $0.02 to $0.05 per gallon is transformative. On a station pumping 150,000 gallons per month (a typical mid-volume independent), that is $3,000 to $7,500 per month. $36,000 to $90,000 per year. That is the difference between a profitable station and one that closes.
The Gap in the Market
Technology for fuel retailers exists, but it solves the wrong side of the equation. Every major solution focuses on retail pricing (what to charge at the pump) rather than procurement (what to pay for the fuel).
| Company | What They Do | What's Missing |
|---|---|---|
| PriceAdvantage | Fuel retail pricing software. Monitors competitor prices, automates price changes to POS systems, pumps, and signs. Division of Skyline Products. Used by Casey's, BJ's Wholesale, Royal Farms. | Entirely retail-side. Helps you set the price at the pump. Says nothing about what you paid for the fuel in the first place. Integrates OPIS rack data for context but does not help the operator buy smarter. |
| OPIS (Dow Jones) | The industry standard for rack price data. Publishes daily rack prices at 220+ terminals. Offers spot market ticker, brand market share reports, and wholesale analytics. | Enterprise pricing. The Spot Ticker product quotes testimonials from buyers purchasing 35 million gallons per year. A single-store operator pumping 1.8 million gallons annually is not the target customer. No procurement optimization, no hedging tools, no jobber markup transparency. |
| DTN (now part of TelVista) | Weather, agriculture, and energy data provider. Offers refined fuel pricing data and supply logistics information. | Also enterprise-focused. Serves large distributors and refiner planning teams, not independent retailers. Data products start at thousands of dollars per year. |
| GasBuddy Business Pages | Consumer-facing gas price app with B2B services. Lets station owners claim and manage their listings, see competitor pricing from crowd-sourced reports. | Consumer data repurposed for business. Shows what competitors charge at the pump. Provides zero insight into wholesale procurement, terminal pricing, or supply optimization. |
| PDI Technologies | End-to-end c-store back office: fuel inventory management (TelaPoint), loyalty programs, supply chain logistics. Acquired GasBuddy in 2021. | Full-featured but designed for chains with 50+ locations and dedicated fuel buyers. Licensing costs and implementation complexity put it out of reach for a 3-store operator. No hedging module. |
The pattern across all five: they serve the sell side, not the buy side. They help retailers optimize what happens after the fuel is in the ground. Nobody is building tools to help small operators buy fuel smarter, compare jobber pricing, time deliveries against spot market movements, or access hedging instruments scaled for their volume.
The Solution
A procurement intelligence platform built specifically for independent fuel retailers with 1 to 20 locations, combining three capabilities that do not exist in any single product today:
1. Terminal price transparency ($99/month per location): Daily rack prices at every terminal within trucking distance of each store (typically 2 to 4 terminals within 100 miles), sourced from OPIS data feeds or built from wholesale market intelligence. The dashboard shows the rack price, the owner's invoice price, and the implied jobber markup. Over time, the system builds a markup history: is your jobber consistent at $0.05/gallon, or do they inflate to $0.09 during supply crunches? That visibility alone changes the negotiation dynamic. A jobber who knows the station owner can see the spread will hold tighter margins.
2. Delivery timing optimization (included in subscription): Rack prices reset daily, and wholesale spot markets move intraday. The platform tracks spot market direction (Gulf Coast RBOB, NYMEX futures, pipeline allocations) and sends alerts when conditions favor buying. If the Gulf Coast spot drops $0.03/gallon on a Wednesday morning and the jobber's rack hasn't adjusted yet, the system tells the operator: order your Thursday delivery now, lock today's rack. If spot prices are spiking and the operator has three days of inventory in the ground, the system says: delay your next delivery, you have capacity to wait for the correction. This is what large-chain fuel buyers do manually with Bloomberg terminals and OPIS Spot Tickers. The platform automates it for an operator who does not have a dedicated fuel buyer on staff.
3. Micro-hedging instruments ($49/month + per-contract fee): This is the most defensible and novel layer. Traditional fuel hedging requires a commodity futures account, a broker relationship, and minimum contract sizes of 42,000 gallons (one NYMEX RBOB futures contract). An independent station pumping 150,000 gallons per month cannot efficiently hedge with instruments sized for airlines and trucking fleets. The platform offers micro-hedging: price collars and fixed-price forward contracts in increments of 5,000 to 10,000 gallons, structured as over-the-counter (OTC) instruments and backed by the platform's own hedging book. The station owner locks in a maximum price for next month's fuel at a 5,000-gallon increment, pays a small premium (typically $0.005 to $0.015/gallon), and eliminates upside price risk on that volume. The platform aggregates thousands of micro-hedges from its customer base and hedges the combined exposure on NYMEX at standard contract sizes, earning the spread between the retail premium charged to operators and the wholesale cost of the hedge.
Original Analysis: The Jobber Markup Opacity Problem
No published research quantifies the information asymmetry cost to independent fuel retailers. So here is a first-pass estimate.
NACS reports average gross margins of 27.2 cents per gallon over five years. But that average masks enormous variance between operators. NACS data shows that retail profitability is inversely correlated with wholesale prices: when wholesale rises fast, margins compress because retailers cannot raise pump prices as quickly as their costs increase. When wholesale falls, margins expand because retailers lower pump prices more slowly than their costs decline.
The question nobody has quantified is: how much of that margin compression comes from the wholesale price itself, and how much comes from the jobber widening the markup during volatile periods?
Consider the mechanics. A refiner posts rack prices daily. The jobber adds a markup and passes the price to the station owner. During stable markets, competition among jobbers keeps markups in a tight band of $0.03 to $0.06 per gallon. But during supply disruptions (hurricane season, refinery outages, the Iran conflict that spiked prices in early 2026), jobbers face their own cost pressures and frequently widen markups to $0.08 to $0.12 per gallon. The station owner, receiving a single price with no breakdown, cannot distinguish between a rack increase and a markup increase.
Using publicly available OPIS rack data and the NACS five-year margin average as anchor points, a conservative estimate of the information asymmetry cost works out to $0.015 to $0.035 per gallon above what a fully informed buyer would pay. On 150,000 gallons per month, that is $2,250 to $5,250 per month in unnecessary cost, or $27,000 to $63,000 per year. For a business where the owner's take-home pay might be $80,000 to $120,000 annually, recapturing even half of that asymmetry cost is material.
This is a rough calculation. The actual cost varies by market, by jobber, and by the operator's negotiating skill. But the structural conditions for information rent extraction are textbook: a fragmented buyer base, a concentrated seller base, an opaque pricing mechanism, and no standardized comparison tool. That combination has produced procurement savings of 3 to 8% in every industry where a transparency platform has emerged (healthcare, auto parts, food service distribution). Fuel is overdue.
Revenue Model
| Revenue Stream | Amount | Notes |
|---|---|---|
| Procurement Intelligence SaaS (per location/month) | $99 | Terminal price transparency, jobber markup tracking, delivery timing alerts. Core product. Monthly billing, no annual commitment required. |
| Micro-Hedging Premium (per location/month) | $49 | Access to micro-hedge instruments. Hedging revenue is separate (below). |
| Hedge spread (per gallon hedged) | $0.005-0.010 | Difference between premium charged to operators and cost of NYMEX hedge. At 50,000 gallons hedged per location per month across 2,000 locations: $500K-1M/month in spread revenue. |
| Jobber marketplace referral fee | $0.005/gallon | Phase 2: connect operators with competing jobbers. Referral fee on switched volume. Requires 5,000+ locations to create a meaningful marketplace. |
| Data licensing | Negotiated | Phase 3: aggregated, anonymized procurement data (markup trends, delivery patterns, regional price elasticity) sold to refiners, jobbers, and industry analysts. |
Unit economics on a single-location operator: Monthly SaaS revenue: $99 (intelligence only) or $148 (intelligence + hedging access). Customer acquisition cost via industry trade shows, NACS advertising, and petroleum marketer association partnerships: ~$800. Annual SaaS revenue at $148/month: $1,776. LTV at 3-year average retention: $5,328. LTV:CAC ratio: 6.7x. If the operator hedges 50,000 gallons/month, add ~$3,600/year in spread revenue, bringing LTV to $16,128 and LTV:CAC to 20.2x.
Market Size
TAM: 122,620 fuel-selling convenience stores in the US. At $148/month (full SaaS + hedging access): $217M/year in subscription revenue. Adding hedge spread revenue at conservative 30% hedging adoption across those stores, with average hedged volume of 40,000 gallons/month at $0.007/gallon spread: an additional $124M/year. Total TAM: ~$341M/year.
SAM: Focus on unbranded and lightly-branded independents with 1 to 10 locations. Approximately 60,000 stores. At $148/month SaaS + proportional hedge spread: ~$165M/year.
SOM (year 3): 3,000 locations at blended $148/month SaaS ($5.3M ARR) plus hedge spread on 25% of customers hedging 40,000 gallons/month ($630K/year). Total year 3 revenue: ~$5.9M. 5% penetration of SAM.
Why Now
Fuel price volatility is at multi-year highs. The Iran conflict that began in early 2026 sent gasoline prices from $3.11 to over $4.50 per gallon in many markets within weeks. C-Store Dive reported that Seven & i Holdings (7-Eleven's parent) warned of "continued declines in fuel volumes and increased volatility in oil prices" in its most recent earnings call. Volatility is the enemy of the independent operator and the friend of anyone selling risk management tools. Operators who rode out 2022's price spikes with no hedging lost money on every gallon during the upswing. The same operators watching 2026's Iran-driven spike are more receptive to hedging than at any point in the past decade.
Credit card fee pressure is squeezing net margins to near zero. NACS reports that convenience stores paid a record $21.3 billion in credit and debit card processing fees in 2025. Because card fees are calculated as a percentage of the transaction amount, higher fuel prices mean higher fees on a product that already carries razor-thin margins. Every additional cent of procurement savings matters more when swipe fees are consuming an increasing share of the gross margin. Operators are looking for cost savings anywhere they can find them.
The market is consolidating, and independents need tools to compete. An OPIS analysis showed that refiner brand market share fell from 40.48% to 39.85% in 2025, while large independent retailers and warehouse clubs gained share by building high-throughput stations. Alimentation Couche-Tard (Circle K) grew to 6,038 locations. The squeeze is coming from both directions: branded refiners pushing their supply agreements, and mega-independents leveraging volume for better wholesale pricing. The mid-market independent without procurement tools is getting crushed from above and below.
Fintech infrastructure makes micro-hedging possible for the first time. Structuring OTC derivatives for small-lot fuel hedging would have required a full commodity trading desk five years ago. Today, firms like Abaxx Technologies and Voxel Bridge provide API-accessible commodity derivatives infrastructure. A platform can build a hedging product without becoming a futures commission merchant (FCM) by partnering with a registered introducing broker and using existing clearing infrastructure. The regulatory pathway exists. The technology exists. What does not exist is a customer-facing product designed for an operator buying 150,000 gallons a month instead of 150 million.
Startup Costs
| Category | Cost | Notes |
|---|---|---|
| Rack price data licensing (year 1) | $120K | OPIS or DTN enterprise data feed for 220+ terminal locations. Largest single cost. Alternative: build proprietary price intelligence from public DOE/EIA data + wholesale market scraping, at lower resolution but 80% lower cost. |
| Software development (6 months, 4-person team) | $320K | 2 backend engineers, 1 frontend, 1 data/quant. Web dashboard, mobile alerts, terminal price aggregation, jobber markup calculator, spot market tracking, hedge pricing engine. |
| Regulatory and legal (commodity derivatives compliance) | $80K | Legal counsel for OTC derivative structuring, introducing broker partnership, NFA registration if needed, customer agreement templates. Required before micro-hedging launch. |
| Hedging capital reserve | $200K | Working capital to maintain NYMEX hedge positions backing micro-hedges sold to customers. Required for credibility and counterparty risk management. Grows with customer volume. |
| Pilot program (50 stations, 3 months) | $25K | Free subscriptions for first 50 stations in Texas and the Southeast (highest independent station density). Goal: validate markup transparency value proposition and collect data on actual procurement savings. |
| Sales and marketing (year 1) | $60K | NACS Show booth ($15K), petroleum marketer association sponsorships, targeted digital ads in c-store trade publications (CSP Daily News, Convenience Store Decisions). |
| Operating buffer (12 months) | $45K | Cloud hosting, LLM API for natural-language delivery timing alerts, customer support. |
| Total | $850K |
Limitations
The $0.015 to $0.035/gallon information asymmetry cost estimate is a construction, not an empirical measurement. It is derived from the gap between NACS-reported average gross margins and the structural conditions that enable jobber markup variability, cross-referenced with published OPIS rack-to-retail spread data. Actual savings from a transparency platform would depend on local market conditions, the number of competing terminals within range, and the operator's willingness to switch jobbers or negotiate. In markets with only one terminal and one jobber (common in rural areas), transparency reveals the markup but provides no competitive alternative. The tool would show the operator exactly how much they are overpaying, with no mechanism to pay less.
The micro-hedging product carries regulatory risk. OTC derivative instruments, even small-lot ones, may require the platform to register as a swap dealer or introducing broker under CFTC regulations. The Dodd-Frank de minimis threshold for swap dealer registration is $8 billion in notional value, which the platform would not approach for years, but the CFTC has interpretive latitude. A conservative legal structure would route all hedges through a registered FCM partner, adding a layer of cost and complexity.
Customer education is a real barrier. Most independent station owners have never encountered a hedge instrument and may view it as speculative rather than protective. The NPR interview with Gill is instructive: these operators think about fuel cost as something that happens to them, not something they manage. Converting that mindset from passive price-taking to active procurement management requires sustained education, not just a software subscription. The pilot program must prove savings in simple, concrete terms ("you saved $2,340 last quarter") before operators will pay $148/month for a tool whose value proposition requires understanding basis risk and forward curves.
The rack price data licensing cost ($120K/year) is a significant fixed expense that does not scale with customers. If OPIS or DTN raises pricing or restricts redistribution rights, the entire cost structure shifts. Building proprietary price intelligence from EIA weekly data and wholesale market sources reduces this dependency but produces lower-resolution data (weekly vs. daily updates, fewer terminals covered).
Strongest Counterargument
Jobbers will kill this. The entire value proposition depends on exposing a markup that distributors have kept opaque for decades. If a critical mass of independent operators gain visibility into terminal-level pricing and start demanding tighter spreads, jobbers will respond. They could refuse to serve operators who use the platform. They could restructure contracts to prohibit price benchmarking. They could vertically integrate, buying stations outright to eliminate the independent operator layer. Most jobbers are regional businesses with 5 to 15 branded trucks serving 50 to 200 stations. They do not have sophisticated legal or technology teams, but they do have the one thing an independent station cannot survive without: a truck that shows up with fuel.
The counterpoint: jobber consolidation and brand switching are already happening without this platform. The OPIS Brand Market Share Report showed refiner brand share declining for three consecutive years as independents and warehouse clubs gained volume. Operators are already leaving underperforming supply relationships when they find better alternatives through word-of-mouth and industry contacts. A transparency platform accelerates an existing trend rather than creating a new one. More importantly, the platform creates value for honest jobbers too. A distributor operating on thin, consistent margins of $0.04/gallon benefits from a marketplace where competitors charging $0.10 during supply crunches are exposed. The platform is not anti-jobber. It is anti-opacity. And the most effective defense against a distribution channel threatening to cut you off is to make the platform so widely adopted that boycotting it means losing customers to competitors who embrace it. That is the classic network-effect playbook, and it has worked in every industry where intermediary margin transparency arrived: real estate (Zillow), auto parts (PartsTrader), healthcare supplies (Medline vs. GPOs).
What You Can Do
If you own an independent gas station: Start tracking your own procurement costs today, with a spreadsheet. Record every delivery: date, gallons, invoice price per gallon, terminal source (if disclosed), and the OPIS rack price for that terminal on that date (you can get delayed rack data from industry newsletters and EIA weekly reports). After 90 days, calculate your average jobber markup. If it exceeds $0.06/gallon on regular unleaded, call your jobber and ask for a meeting. The simple act of demonstrating that you track this number changes the relationship. If your markup is consistently above $0.08 during periods of rising prices, request quotes from a second jobber. In most markets, switching takes 30 to 60 days and requires no infrastructure changes.
If you are a fuel marketer or petroleum industry technologist: The unbranded independent segment (roughly 60,000 stations) is the largest underserved market in fuel retail technology. Every major vendor, from PriceAdvantage to PDI to OPIS, is selling downstream (retail pricing) or selling to the top of the market (large chains, refiners). The buy-side tools for small operators are a green field. Start with the transparency product ($99/month, no hedging complexity), validate that operators will pay for markup visibility, and add hedging as a Phase 2 product once you have 1,000+ subscribers and the data to prove savings claims. Partner with a state petroleum marketers association (SIGMA, PMAA) for distribution, because these associations already advocate for independent operators and would welcome a tool that validates their members' complaints about wholesale pricing opacity.
If you are an investor: The risk-adjusted opportunity here is the SaaS subscription, not the hedging spread. A $99/month transparency product for 60,000 addressable operators is a $71M SAM with straightforward SaaS unit economics (6.7x LTV:CAC) and no regulatory risk. The micro-hedging layer is the upside play, with higher revenue potential but genuine CFTC compliance questions and counterparty risk management challenges. A seed-stage investment should fund the SaaS product through 1,000 subscribers, with the hedging module as a Series A milestone contingent on regulatory clarity and proven demand. Comparable exits in energy tech SaaS (Genscape acquired by Wood Mackenzie for $364M in 2019, OilX Series B at $55M valuation in 2024) suggest that energy data platforms with proprietary pricing intelligence command 8 to 12x revenue multiples.
The Bottom Line
Sixty-four thousand single-store gas station operators in the United States buy $2 to $5 million worth of fuel per year and have less visibility into their procurement costs than a restaurant owner has into the price of chicken wings. The wholesale fuel pricing chain, from spot market to rack to jobber to station, is a textbook case of information asymmetry sustaining intermediary margin. Every other industry with this structure has eventually produced a transparency platform that compressed spreads and shifted value to the buyer. Fuel is one of the last holdouts, not because the technology is hard, but because the buyer is fragmented, unsophisticated, and has never been anyone's target customer. An operator who pumps 150,000 gallons a month and saves $0.03 per gallon through better procurement generates $54,000 in annual savings: more than enough to justify a $1,776 software subscription, and more than enough to build a business on at scale.